Kuaishou's Kling AI reached a 300 million annualized revenue run rate in January 2026 and is raising 3 billion at an $18 billion valuation ahead of a Hong Kong listing — the first Chinese AI application to prove recurring global revenue at scale, even as OpenAI retired its rival Sora. The bottleneck has moved past model research: it is now the multilingual commercial and creative-market leaders who can grow AI video revenue across Tokyo, Seoul, London and Los Angeles. A recruitment specialist at SunTzu Recruit describes a shortage that has become structural.
Robotaxi fleets from China run in Dubai and Doha, but executives able to run them across regulators are scarce. Gulf roles, pools and fill times, mapped.
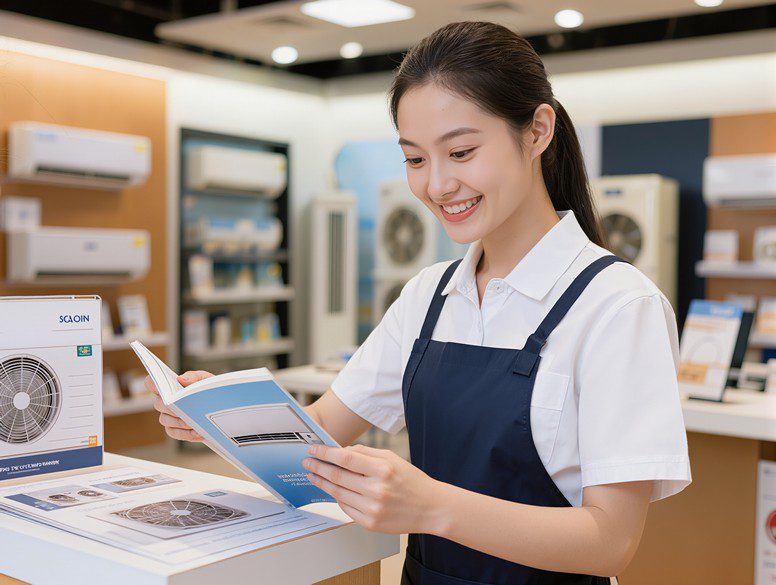
China’s air conditioner exports to the EU surged 43.2% in H1 2026 amid record heat waves and structurally low local penetration. Leading Chinese brands are shifting from pure export to full local operations, including R&D centers, manufacturing plants and service networks. The critical bottleneck is now scarce cross-border localization executives who can build and run in-market operations, with demand far outpacing the limited talent pool.
China’s AI job postings surged 12-fold year-on-year in early 2026, with AI roles now accounting for over 26% of all new-economy positions. The industry bottleneck has shifted from foundational model research to AI deployment and production talent. Roles like MLOps engineers and AI solution architects are extremely scarce, requiring a rare mix of model expertise and industry domain knowledge, with average search cycles exceeding six months.
Chinese quant hedge funds more than doubled their assets under management to 2.6 trillion yuan (US$384 billion) in under a year, as AI-driven strategies beat human traders by a wide margin. Yet the industry now faces a constraint harder than capital: finding enough quantitative researchers, risk officers, and portfolio managers in Shanghai and Beijing to keep the machines running. SunTzu Recruitment, a China-based executive search firm, says the supply of bilingual quant talent has not kept pace with the money flowing in.
Between them, the two companies that dominate AI-assisted software development are worth close to 90billion,morethanseveralenterprise−softwaregiantstheyarequietlydisplacing.Cursor,builtbyAnysphere,doubleditsannualizedrevenuetoabout2 billion […]
Chinese AI firms have built capable foundation models, with capital pouring into application‑layer businesses. However, experienced go‑to‑market, solutions architecture and enterprise AI revenue executives are in acute shortage. Senior searches in Shenzhen and Shanghai commonly exceed six months amid cross‑border talent competition.
Battery gigafactories are springing up across Morocco, India, the UAE and beyond, with capital and construction permits ready. Yet experienced executives capable of building, financing and operating multi‑gigawatt facilities remain scarce. Poaching from data‑center firms lengthens hiring cycles to more than seven months for key battery‑storage leadership roles.
China's tea chains now run roughly 5,000 stores across more than a dozen countries, yet Mixue Group's overseas network contracted by 428 stores in 2025 — its first-ever annual decline — while Chagee plans 200 new overseas stores in 2026 and is shifting from light-asset franchising to heavy-asset localization. The binding constraint is no longer storefronts or supply chains; it is local country managers and compliance executives. A recruitment specialist at SunTzu Recruit in Shanghai estimates the qualified bilingual retail-operations talent pool across Southeast Asia and Seoul numbers in the low hundreds.
Chinese biopharma companies signed $75 billion in out-licensing deals in the first five months of 2026 — up from near zero before 2020 — but the executive talent supply chain to manage global partnerships, clinical operations, and cross-border regulatory strategy is stretched to the breaking point.